Wind turbine orders surge as Chinese exports accelerate
The global wind market delivered a record year for wind turbine orders in 2025. According to the latest analysis from Wood Mackenzie, total commercial orders reached 215 GW, marking the second-highest annual volume ever recorded. The milestone was fueled primarily by a boom in overseas contracts signed by Chinese original equipment manufacturers.
Chinese-made turbines have intensified competition with Western manufacturers in recent years, backed by strong domestic industrial policy and state support. In 2025, however, a slowdown in new domestic installations following changes to China’s incentive regime pushed manufacturers to accelerate exports. International wind turbine orders for Chinese OEMs increased 66% year over year.
“Leading Chinese OEMs are securing more orders in high-growth markets such as the Middle East, India and Latin America, leveraging the rapid rollout of 10 MW-plus platforms to capture market share,” said Finlay Clark, Principal Analyst at Wood Mackenzie.
Europe faces mounting competitive pressure
For Europe’s wind industry leaders, the expansion of Chinese wind turbine orders presents a significant challenge. Beyond competing with lower-cost manufacturing, European OEMs lack comparable production flexibility. Chinese manufacturers benefit from tightly integrated domestic supply chains and ready access to local resources, advantages that Western companies struggle to match.
Analysts warn that the sector could replicate the trajectory seen in the solar market, where European producers lost ground both internationally and within their home market.
In some regions, Chinese suppliers have nearly saturated new contracts. In the Middle East and Africa, developers prioritized early availability of 10 MW-class models to minimize costs on gigawatt-scale projects. As a result, Chinese OEMs captured 95% of regional capacity in 2025. Saudi Arabia confirmed this shift, awarding Goldwind a 3.1 GW order across two sites, the largest single turbine order ever recorded in the region.
At the same time, Europe posted stronger-than-expected onshore wind turbine orders, up more than 60% following regulatory reforms in Germany that unlocked project approvals. In 2025, Germany authorized 21 GW of onshore capacity, double the 2024 total.
Top ten wind turbine manufacturers in 2025
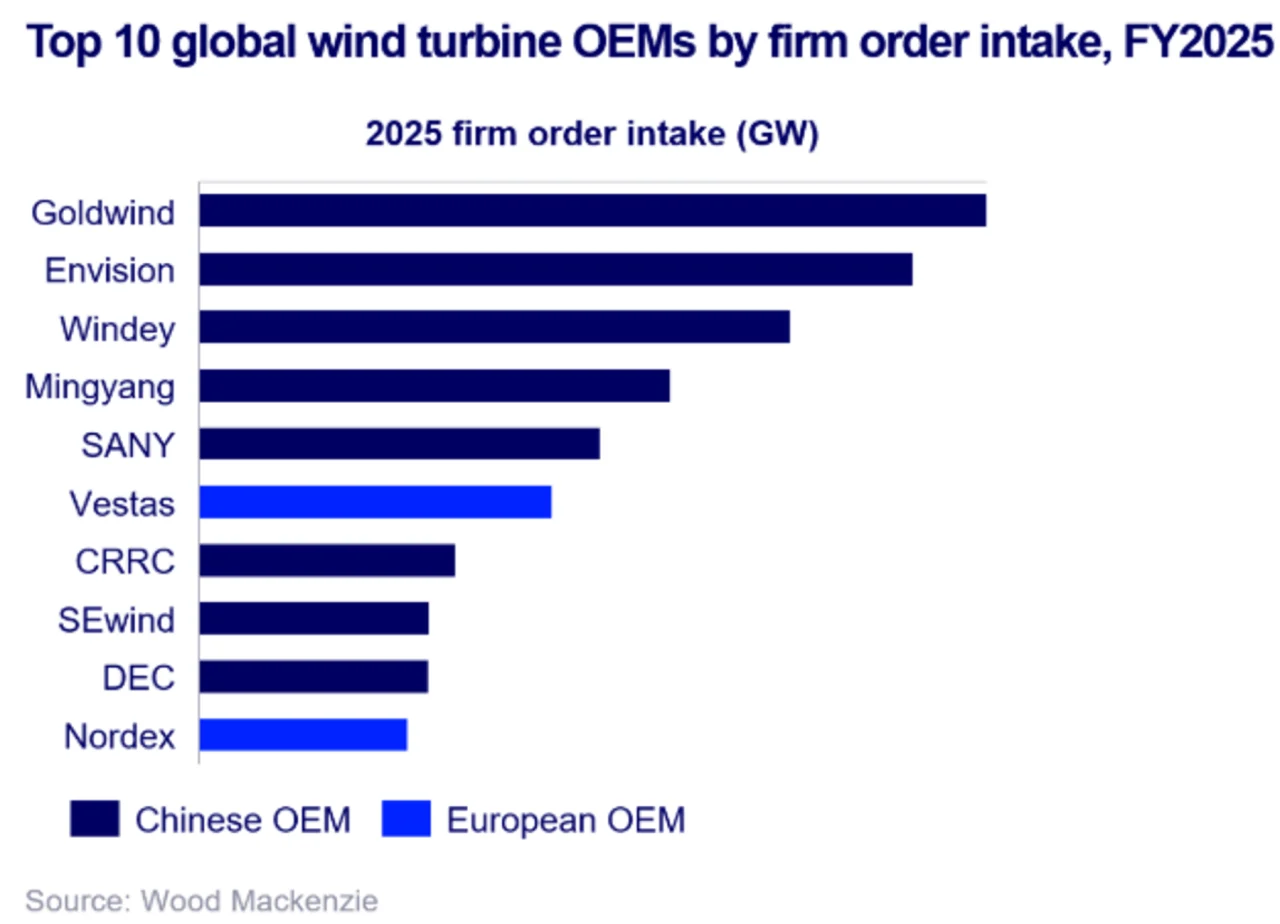
The global ranking of wind turbine manufacturers by order intake once again reflects the dominance of China, which holds eight of the top ten positions. Goldwind leads the list, followed by Envision and Windey, even though most of their contracts remain concentrated in the domestic market. The only European OEMs in the top ten are Vestas and Nordex, ranked sixth and tenth, respectively.
“China secured more than 150 GW of wind turbine orders in 2025, a strong result despite a 15% decline from the 2024 peak,” said Yuan Ren, Senior Analyst for Power and Renewables.
Turbine pricing and geopolitical headwinds
Despite intense competition, wind turbine prices have remained stable and above 2022 and 2023 averages. New geopolitical dynamics are complicating the outlook. The European Union’s carbon border adjustment mechanism and new U.S. tariffs have increased logistics costs for steel components.
Under the CBAM framework, turbine costs in Europe could rise by a few percentage points. However, developers and regulators continue to push for lower prices to safeguard project profitability in an increasingly competitive market.