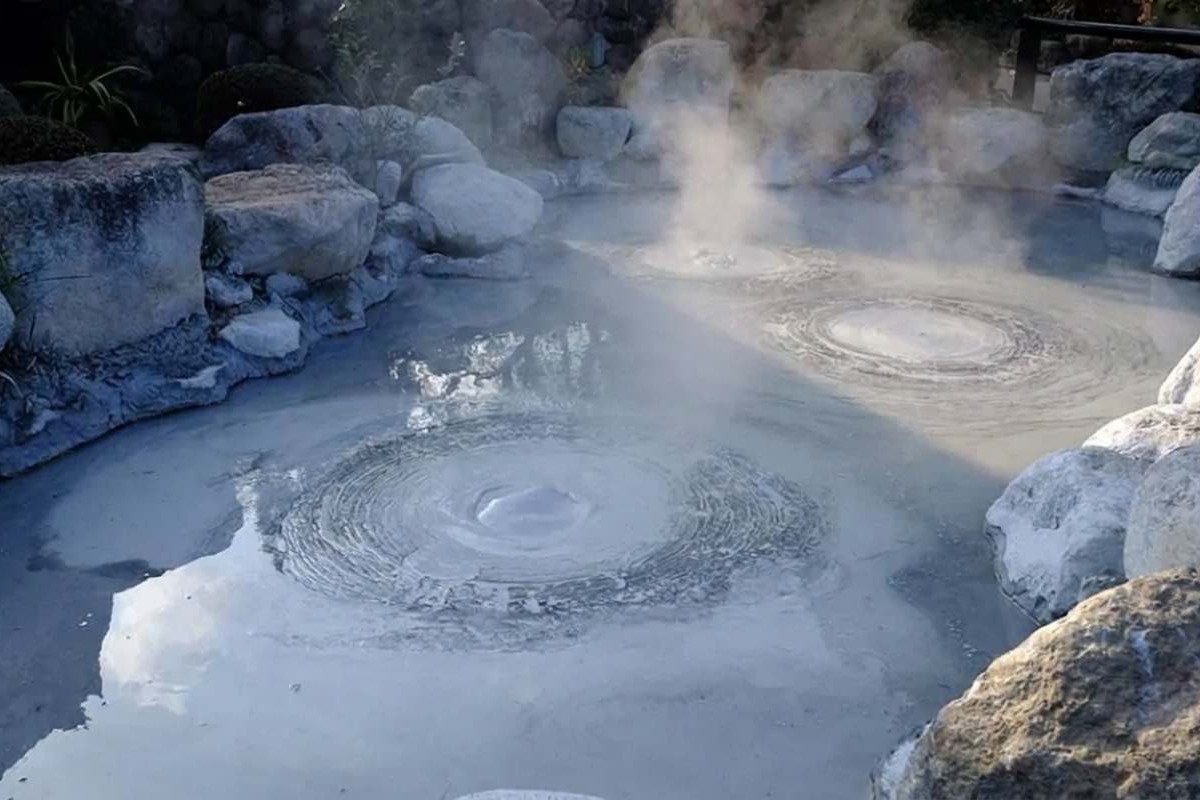
Natural hydrogen as a strategic option in the energy transition
Natural hydrogen could play a strategic role in the global energy transition as investment in synthetic low-carbon hydrogen faces mounting headwinds. The outlook comes from an analysis by Simon Flowers, Chairman and Chief Analyst at Wood Mackenzie and author of The Edge, alongside Kate Adie, Research Analyst in the Subsurface team.
The low-carbon hydrogen sector experienced a difficult 2025. Final investment decisions fell 30% year over year in capacity terms, while project cancellations nearly tripled. The issue is not a lack of demand but the challenge of driving costs down.
In this context, governments and companies are exploring new options. Unlike green or blue hydrogen, which require energy-intensive conversion processes, natural hydrogen is already present in geological formations. It can theoretically be used at the wellhead, potentially at a much lower cost.
What is white hydrogen and how does it form
Natural hydrogen consists of hydrogen molecules generated through ongoing geochemical reactions within hard rock formations. It follows migration and accumulation patterns similar to those of oil and gas, which is why it is sometimes referred to as white hydrogen.
Its physical properties distinguish it from hydrocarbons. The molecules are small and light, and its volumetric energy density is significantly lower than that of natural gas. This means much larger resource volumes are needed to match the energy value of a typical gas discovery.
The overall potential therefore depends on identifying substantial and technically recoverable accumulations. Advanced geoscientific expertise and established subsurface exploration techniques are essential to assess and develop these resources.
The current state of exploration
The sector remains at an early stage. After years of theoretical research, drilling activity is beginning to accelerate. The United States leads exploration efforts, followed by Australia, while Canada and France have active campaigns underway.
Wood Mackenzie reports around 60 announced projects globally, though most are still in the study or surface data collection phase. Initial wells will be critical to proving that dedicated exploration programs can deliver tangible results. Many more wells will be needed to understand the true scale of the resource base.
If early drilling proves successful, broader development opportunities could emerge.
Who is investing in geological hydrogen
In the United States, the landscape is dominated by startups and small-cap companies. Colorado-based Koloma is the leading operator and has secured 85% of the roughly $400 million in early-stage capital mobilized so far.
Major mining, oil and gas companies have not yet entered directly. Some large players, including Fortescue, Rio Tinto and BP Ventures, have taken strategic positions through targeted investments, opting to wait for clearer evidence of technical and commercial feasibility before committing significant capital.
The required capabilities align closely with those of the oil and gas industry. However, strategic priorities among major energy companies remain focused on strengthening upstream portfolios over the next decade, making large near-term capital allocations to low-carbon molecules, including natural hydrogen, unlikely.
Regulatory frameworks and market access
As with oil and gas, robust regulatory frameworks are essential. Jurisdictions with clearer rules are seeing more activity. In the United States, simplified access to mineral rights has created a supportive environment. Australia has advanced progressive legislation that has facilitated exploration.
In Europe, the regulatory landscape is more fragmented. France moved quickly to recognize hydrogen as a regulated energy molecule, while restrictive drilling regulations in Spain have slowed progress.
In many markets, it remains unclear whether natural hydrogen can access the same support mechanisms available to green and blue hydrogen. Clarity around subsurface ownership and mineral rights is critical to attracting investment. The Middle East is cited as a notable example, with promising geology and strong demand but no clearly defined regulatory framework.
How much could natural hydrogen contribute
Wood Mackenzie does not currently include natural hydrogen in its base supply forecasts. However, in a successful exploration scenario, the technical potential of announced resources could reach 20 Mtpa by 2050, equivalent to about 12% of projected global low-carbon hydrogen supply at that time.
The theoretical advantage is clear. Without the need for energy conversion processes, wellhead costs should be lower than those of green and blue hydrogen. The key question remains whether natural hydrogen can reach end markets in a cost-competitive way or whether direct use at the source will be required. Demonstrating a sustainable commercial model will be the decisive challenge.